Most Canadian business owners did not start a company to do paperwork. Yet it’s the numbers in that very paperwork that decide how long the business stays afloat and, eventually, when they hire accounting services. Small business financial management in Canada comes down to a handful of habits—keeping money separate, recording every transaction, watching cash, and preparing for tax before deadlines arrive.
But the good news is that none of it requires an accounting degree, whether you run a shop, a studio, or a trade crew. This guide walks through each habit in plain terms, so you can run tighter books, avoid surprises from the Canada Revenue Agency (CRA), and make decisions with real figures in front of you.
6 Important points to Manage Business Finances
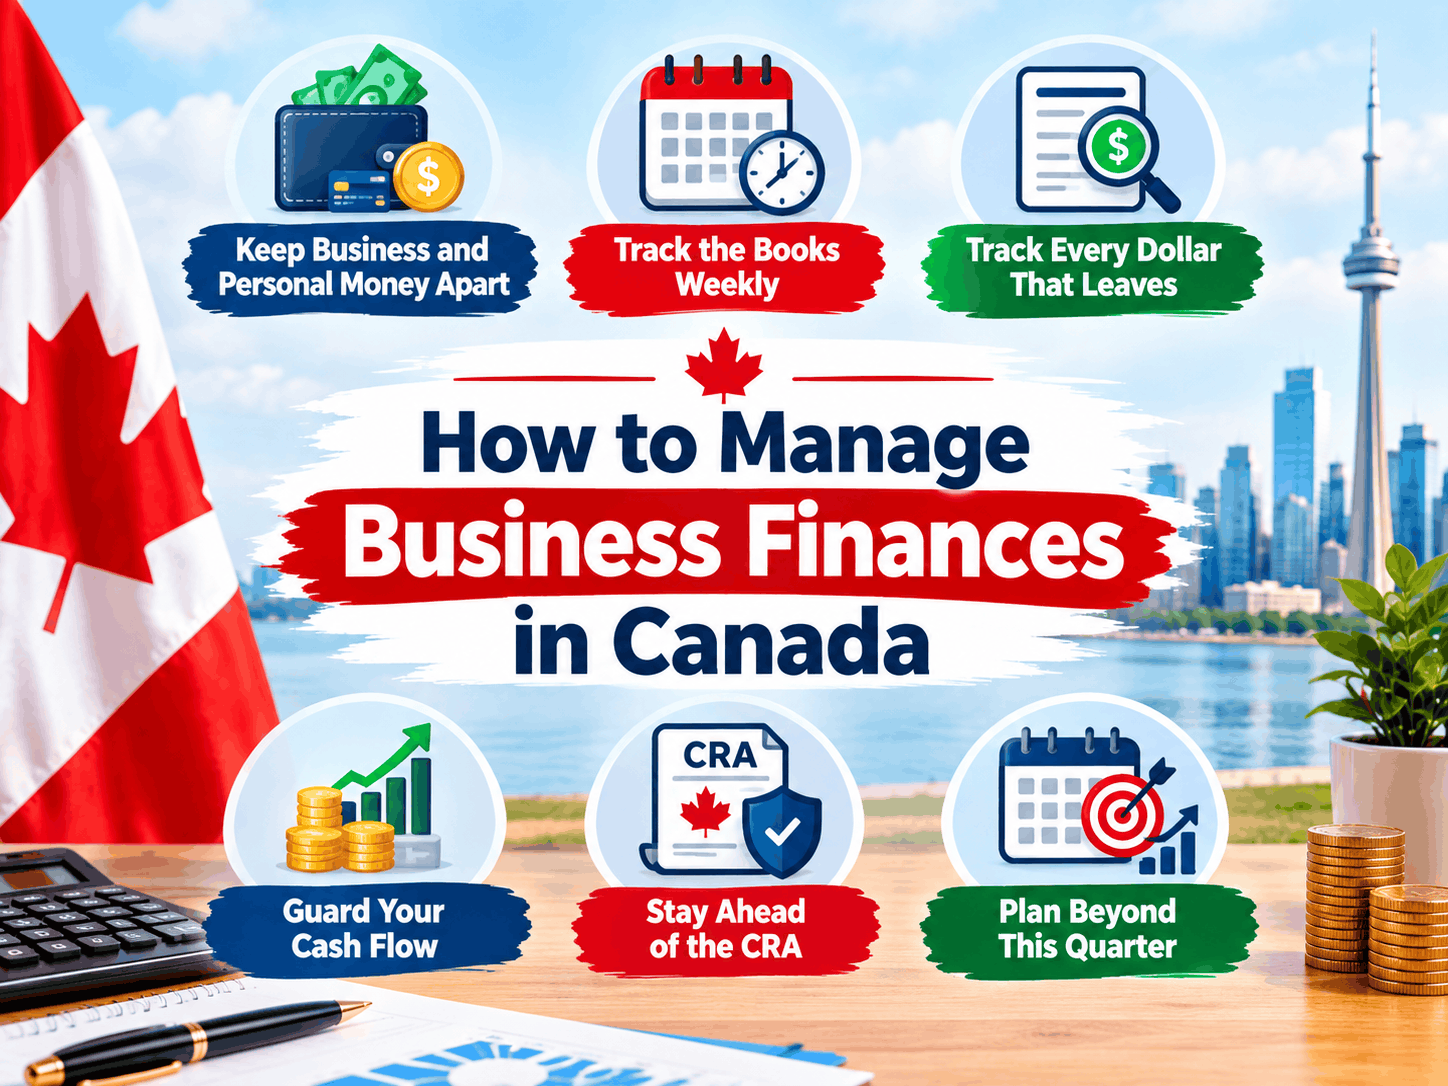
1. Keep Business and Personal Money Apart
Organized small business finances in Canada start with separation. Open a business checking account and, if possible, a business credit card. Pay yourself on a set schedule instead of dipping into the account whenever you need cash.
These clear lines make year-end work faster, leave a tidy trail if the CRA asks questions, and show lenders that the business stands on its own.
2. Track the Books Weekly
Set a fixed time each week to record sales, bills, and payments. Cloud software such as QuickBooks Online, Xero, or Wave syncs with your bank and handles most of the typing.
Some of the most useful small business accounting tips in Canada are simple: reconcile accounts monthly, send invoices the day work finishes, and follow up on late payers quickly. Keep records for six years from the end of the tax year they relate to, which is what the CRA expects.
3. Track Every Dollar That Leaves
Business expense tracking in Canada matters because a deduction only counts when you can prove it. Photograph receipts as soon as you get them and store them in a digital folder. Assign each expense in a category, such as fuel, software, or professional fees, when you log it.
Keep a mileage log if you use a vehicle for work. Receipts also support your GST/HST input tax credits, so a lost slip can cost you twice.
4. Guard Your Cash Flow
Sound business financial management in Canada watches cash first, because profit on paper does not pay rent. Build a simple forecast of expected income and outgoings for the next three months and revisit it every few weeks.
Ask clients for deposits, shorten payment terms, and negotiate extra time to pay suppliers where you can. Hold a reserve covering a few months of fixed cost so a slow season never pushes you toward expensive borrowing.
5. Stay Ahead of the CRA
Good business tax management in Canada means no scrambling at filing time. Sole proprietors file personal returns by June 15, but any balance is due April 30.
Corporations generally have six months after the end of their tax year to file their T2 corporate income tax return. However, the balance of tax owing is generally due within two months after the tax year-end. Qualifying Canadian-controlled private corporations (CCPCs) may have three months to pay if they meet the CRA’s eligibility conditions. Check the CRA’s corporation balance-due date guidelines to confirm your payment deadline.
Move a slice of every customer payment into a separate savings account so the tax bill never ambushes you.
6. Plan Beyond This Quarter
Financial planning for a small business in Canada works best with written targets. Set revenue and profit goals for the year, then split them into monthly numbers.
Decide in advance when you hire, buy equipment, or raise prices. Compare results against the plan each quarter and adjust. Many owners also use this stage to review incorporation, retirement savings, and compensation choices with a professional.
Build the Habits, Then Get Support
Managing business finances in Canada rests on routine: separate accounts, steady bookkeeping, tracked expenses, a cash forecast, and early tax planning. Set these up now, and year-end stops being a scramble.
If you want help building the systems or reviewing what you already have, Pitre James Business & Tax, based in Kelowna, supports business owners with accounting, tax, and planning. Reach out for a review before your next filing deadline.
